

CreditWise from Capital One
4.6

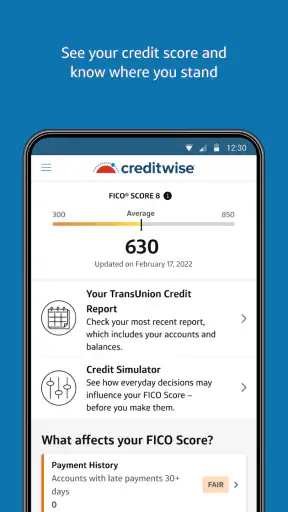
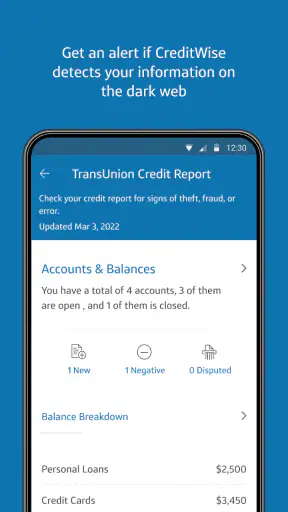
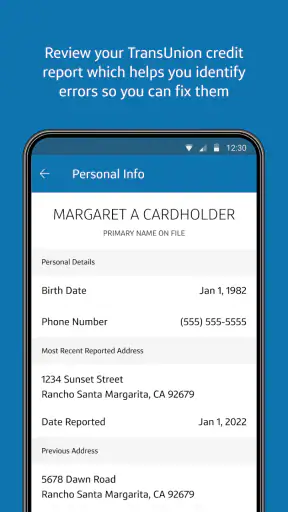
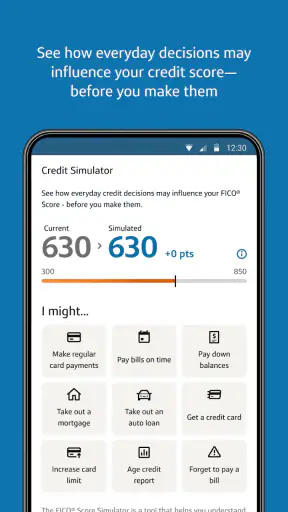
CreditWise from Capital One is the kind of finance app I would install when I want a clearer view of my credit without paying for a separate monitoring service. It focuses on credit information rather than trying to become a complete banking replacement, and that narrower purpose is one of its biggest strengths. I found it most useful as a regular check-in tool: something I could open, understand quickly, and use to make calmer decisions before applying for credit or changing my borrowing habits.
The app is free, aimed at everyone, and developed by Capital One Services, LLC. Its store presence is substantial, with over five million installs, an average rating of 4.6, and more than one hundred thousand ratings. Those figures do not automatically make an app perfect, but they do suggest that CreditWise has become a familiar option for people who want access to credit information on a phone.
How CreditWise feels in everyday use
I find CreditWise most useful when I decide in advance what I’m checking, rather than opening it whenever I feel uneasy about money. A quick review can help me spot something worth following up, while a focused look at one question—such as whether I recognize recent activity—keeps the visit practical. That routine also makes it easier to think about what information I’m comfortable reviewing in a finance app.
A focused start instead of a crowded financial dashboard
My first impression is that CreditWise makes more sense when I treat it as a credit-monitoring companion, not as a full personal-finance command center. Many banking apps combine balances, transfers, cards, loans, spending charts, rewards, and credit education in one place. That can be convenient, but it can also make a simple question harder to answer: “Has anything important changed with my credit?” CreditWise is more focused on that question.
That focus affects perceived speed. An app with a narrower job generally feels easier to approach because I am not searching through unrelated account tools before reaching the information I want. I would expect the opening experience to be most comfortable for quick checks rather than long financial sessions. When I want to review my credit position, I prefer a screen that does not make me sort through a complete banking ecosystem.
There is also a psychological benefit to the focused design. Credit can feel intimidating when every screen uses financial terminology or presents several decisions at once. CreditWise is better suited to a short routine: open the app, review the current picture, look for a meaningful change, and close it. That makes it practical for someone who is learning how credit works and does not yet want a complicated financial planner.
Speed expectations for a credit-monitoring app
It is important to set the right expectation. Credit information is not the same as a live bank balance. A credit-monitoring app depends on information becoming available through the credit-reporting process, so I would not use CreditWise to judge whether a payment made moments ago has already changed my credit standing. The app can be quick to open and navigate, but the underlying information may follow a different timetable from the action that caused it.
This distinction matters in everyday situations. If I pay down a card before applying for an apartment, I would not assume that opening CreditWise immediately afterward proves the payment has been reflected. The useful workflow is to check the app regularly, understand the latest available picture, and avoid treating a single refresh as an instant financial laboratory.
For quick reviews, that is not really a weakness of CreditWise; it is a limitation of the subject it covers. The app can present information efficiently, but it cannot turn credit reporting into a real-time feed. Use it for awareness and trend-checking, not as a live approval simulator.
What happens during heavier use
CreditWise is not an app I would expect to keep open for hours. Its natural workload is a handful of short visits: checking for changes, reviewing credit guidance, or preparing for a financial decision. That makes resource demand less concerning than it would be in a game, video editor, or investment app with constant live updates.
The heavier moments are more likely to come from the user’s workflow than from continuous processing. For example, I might compare the current credit picture with a previous visit, read several educational explanations, and then move between the app and a lender’s application. On a smaller phone screen, that can feel more demanding because I am mentally connecting several pieces of information, even if the app itself remains simple.
My practical advice is to avoid turning one visit into a frantic investigation. If something looks different, first note what changed, then check the surrounding details before drawing a conclusion. A credit-monitoring app is valuable when it encourages methodical checking. It becomes less helpful when I repeatedly refresh it expecting an immediate answer to a recent payment, inquiry, or account update.
Stability and recovering from interruptions
Finance apps earn trust through predictability. I want to be able to return after a phone call, a short interruption, or a switch to another app without losing the thread of what I was reviewing. CreditWise is best approached as a read-and-review tool, so recovering from an interruption should be relatively straightforward: reopen it, sign in if needed, and continue checking the latest available information.
I would still avoid making an important credit decision while multitasking heavily. If a notification interrupts me while I am reviewing a change, I would start that review again rather than rely on memory. That is not because the app is necessarily unstable; it is simply a sensible habit for financial information. A clean second look is better than acting on a half-read screen.
There is a useful recovery principle here: separate app recovery from financial recovery. If the app closes or the session needs to be reopened, that is a technical inconvenience. If the information looks unfamiliar, that is a financial question requiring care. Reopening CreditWise may restore access to the screen, but it does not explain every change automatically. I would use the app as an early warning and then investigate through the appropriate account or credit documentation when necessary.
Device constraints and operating-system support
The current version is 1.150.0, and the listed minimum operating-system requirement is iOS 11 or later. That makes the app relevant to people using older Apple devices that still meet that requirement, while anyone on an earlier system would need to consider an upgrade before expecting to use it. The requirement is worth checking before downloading, especially if the phone is kept for basic tasks and has not received recent system updates.
On a newer phone, I would expect the main constraint to be screen size rather than raw capability. Credit information is easier to review when text is comfortable to read and I can pause over unfamiliar terms. On a compact or older device, I would take extra care with scrolling and confirmation steps. A finance app should not be judged only by whether it opens; it should also be comfortable enough that I do not rush through an important detail.
Storage demand is not the main concern for this kind of app. CreditWise is not built around large media files or demanding graphics. The more relevant device considerations are operating-system compatibility, a stable connection when information needs to be retrieved, and enough battery to complete a secure financial check without interruption.
A realistic weekly scenario
Imagine I am planning to apply for a new credit card. I would open CreditWise several days before submitting anything, review the current credit picture, and make a note of anything I do not recognize. I would not use the app to guarantee approval, because a lender can apply its own criteria and may evaluate information differently. Instead, I would use it to avoid walking into the application blindly.
After applying, I would return later to check for a new inquiry or another notable change. I would not expect the result to appear instantly, and I would not repeatedly refresh the app throughout the day. A measured routine is more useful: check, record what seems different, and follow up through the relevant lender or credit-reporting channel if the change needs explanation.
This scenario shows where CreditWise fits well. It gives me a convenient place to build credit awareness before and after a major action. It does not replace reading the terms of a card, contacting a lender, or reviewing all available records when identity theft or an error is suspected.
Useful habits that make the app more valuable
The first habit I recommend is establishing a personal baseline. I would check the app at a calm time, note the general state of my credit information, and then use future visits to identify meaningful differences rather than reacting to every small fluctuation. This turns a vague worry into a comparison process.
The second is to separate education from urgency. If CreditWise presents an explanation of a credit concept, I would read it when I am not under pressure to submit an application. Learning terminology in advance makes later alerts easier to understand. Waiting until a lender is asking for a decision is the worst time to discover that I do not understand what a particular item means.
The third is to use the app as a prompt for account security habits. If I notice a change I cannot connect to my own activity, I would not simply dismiss it because the app is convenient. I would check recent account messages, contact the relevant provider through an official route, and protect my accounts as needed. CreditWise can help me notice that something deserves attention, but the response still belongs to me.
A fourth, less obvious trade-off is that frequent checking can create unnecessary anxiety. Credit information can change for reasons that do not instantly translate into a clear action. I would set a reasonable checking routine instead of opening the app every time I feel uncertain. The goal is informed attention, not constant surveillance of my own finances.
Where it beats usual alternatives
Compared with checking credit only through a bank or card issuer, CreditWise can be appealing because its purpose is easier to understand. A banking app may show useful credit information, but it is often surrounded by offers, balances, payment tools, and account management. CreditWise feels better suited to someone who wants a dedicated credit check without making a banking relationship the center of the experience.
Compared with paid credit-monitoring services, the free price is a meaningful advantage for a casual user. I would not pay for a large bundle of financial tools if my actual need were simply to understand my credit position and notice important changes. The trade-off is that a specialized paid service may offer a broader package or a different depth of reporting, depending on the person’s needs. CreditWise is strongest when its focused scope already covers the job.
Compared with relying on a score shown by a lender, it is more useful as a personal habit because I can check it before I am in the middle of an application. That said, I would never assume that the number or information I see guarantees the exact outcome of a lender’s decision. Different organizations can use different models, timing, and criteria. The app helps me prepare; it does not make the decision for the lender.
Who should use it, and who should skip it
I would recommend CreditWise to someone who wants a free, approachable way to pay attention to credit without committing to a paid monitoring plan. It is especially suitable for people preparing for a major financial step, learning the basics, or trying to notice unfamiliar activity earlier. Its Everyone age rating also makes it broadly accessible, although younger users should still have appropriate guidance when dealing with financial decisions.
I would be more cautious recommending it as the only tool for someone managing several complex accounts, investigating a suspected identity problem, or needing a complete budgeting and transaction-management system. In those cases, a bank’s tools, a dedicated budgeting service, or direct contact with the relevant institutions may be more appropriate. CreditWise can be part of that process, but I would not mistake it for the entire process.
It may also be a poor fit for someone who expects every credit event to update immediately. If instant confirmation after a payment is essential, this app will not remove the timing gap built into credit reporting. The right user is comfortable treating the information as a monitored snapshot that becomes useful through repeated, sensible checks.
My performance verdict
From a performance perspective, CreditWise benefits from having a clear, limited purpose. I would expect it to feel lighter and easier to revisit than a broad financial super-app because the experience is centered on credit awareness rather than every aspect of money management. Its most important performance quality is not flashy speed; it is whether I can reach understandable information without friction and return to it when a financial decision requires context.
The main limitations are tied to expectations. The app cannot make credit reporting instantaneous, cannot promise a lender’s decision, and cannot replace careful investigation when something looks wrong. Older devices also need to meet the iOS 11 minimum, and a small screen may make detailed reading less comfortable. These are practical boundaries, not reasons to dismiss the app.
CreditWise from Capital One is free, focused, and easy to justify for routine credit awareness. I would install it for a simple purpose: to build a regular habit of checking my credit picture before important decisions, without paying for a larger financial package I may not use. Its current version, 1.150.0, shows that it remains an actively maintained option in this category. If you want a focused credit check rather than a complete money-management suite, this is a sensible place to start.
4.6
40.63K Reviews
Pros
- Free credit score tracking with no impact on your credit.
- Provides alerts about changes to your TransUnion credit report.
- Credit score simulator shows how actions may affect your score.
- Identity monitoring can flag exposed personal information.
- Simple interface makes credit information easy to understand.
Cons
- Features primarily use TransUnion data
- not all credit bureaus.
- Some monitoring tools may require additional personal information.
- Credit score updates may not reflect every lender’s scoring model.
- Offers for Capital One products can feel promotional.
- Availability and features may vary by location and eligibility.


